D-Tools Data Shows Mid-Sized AV Integrators Losing Ground in 2026
2026-09-21 · via invidis
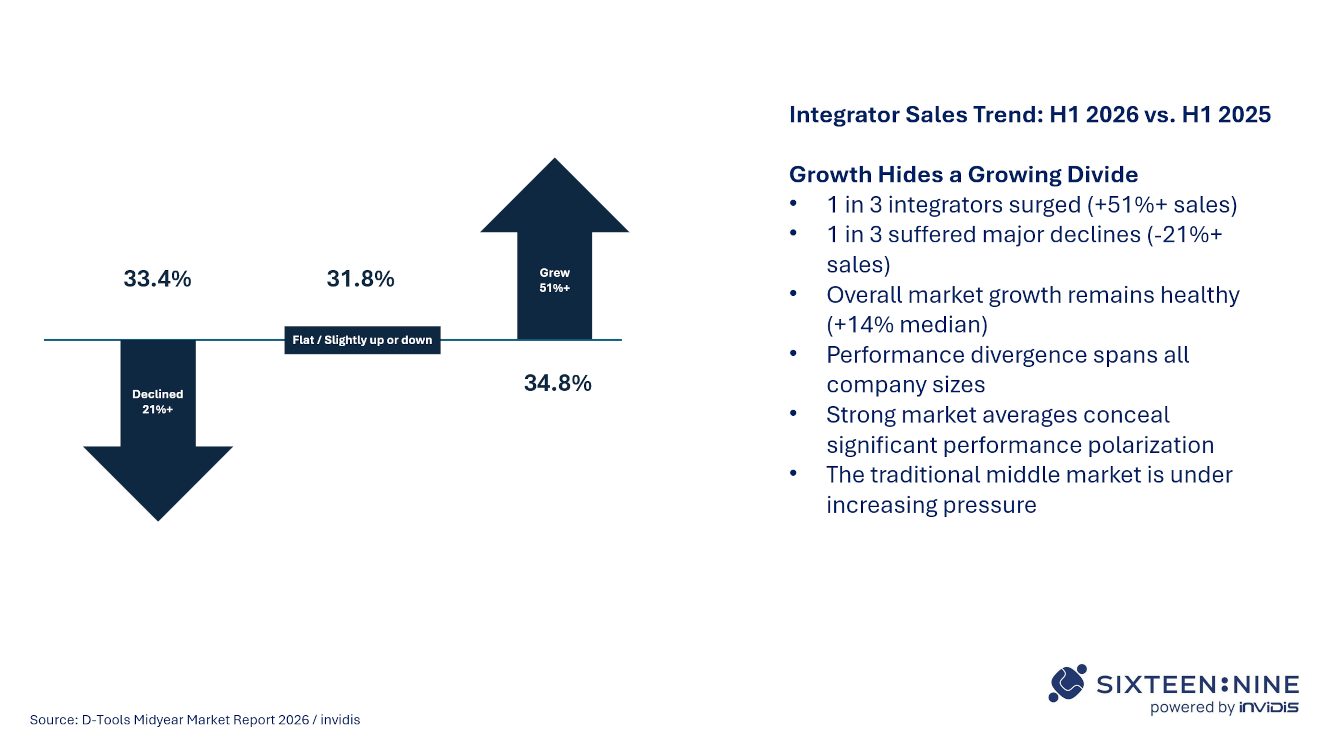
New data from D-Tools, a US-based management platform for AV integrators, shows the industry's healthy headline growth figure is masking a widening split between winners and losers, with mid-sized integrators bearing the brunt of the pressure.
According to D-Tools' 2026 Midyear Market Report, median sales among participating integrators rose 14% in the first half of 2026 compared with the same period in 2025. But among the more than 1,500 companies tracked, 34.8% grew sales by at least 51% while 33.4% saw declines of 21% or more. The rest were roughly flat.
"The market growth is solid, but it's not the whole story," said Jason Knott, Data Solution Architect at D-Tools. "Our data shows the market is splitting in two."
The report singles out one contract band as the weakest performer: projects averaging USD 25,000 to 50,000, which declined 16.1%, worse than any other category. Projects under USD 10,000 grew, and those above USD 50,000 also expanded. That USD 25,000 to 50,000 range has long been the core business for regional integrators, large enough to need professional design and installation but small enough not to require the scale of a global service organisation.
For anyone running or buying signage networks, the relevant point is where that pressure is coming from. D-Tools points to two forces squeezing the middle. At the low end, digital signage and AV are increasingly sold as productised bundles, screens, players, software and support packaged by manufacturers, IT resellers, telecom operators or online marketplaces, sometimes as a subscription rather than a capital project. Menu boards folded into POS platforms are one example the report cites. At the high end, enterprise buyers are favouring providers with managed service capability, international coverage and lifecycle management, which tends to favour larger integrators and technology service companies.
D-Tools also found that integrators generated 19% more proposals and signed 17% more contracts in the period, but close rates stayed flat. That suggests companies are winning more business mainly by chasing more opportunities, not by converting prospects more efficiently, a sign of intensifying competition and pricing pressure rather than genuine demand strength.
The report does not claim mid-sized integrators are finished, but it does suggest that standing still carries more risk than before. It frames the successful path as either scaling up through acquisitions, managed services and broader geographic reach, or specialising deeply in a vertical, software integration or niche expertise. Companies stuck between those two positions, the report suggests, are the ones losing share. The announcement does not name specific mid-sized integrators affected or break out figures by region.
The announcement in full
Reproduced from invidis for reference. Digital Signage Magazine did not write the text below.
For years, the AV integration industry has been defined by steady consolidation at the top and fierce price competition at the lower end. Now, fresh data from D-Tools - the US-based management platform for integrators - suggests that this pressure is translating into measurable business performance. The industry's median sales growth remains healthy, yet the underlying distribution tells a very different story.
According to the D-Tools 2026 Midyear Market Report , median sales among participating integrators increased by 14% during the first half of 2026 compared with the same period in 2025. At first glance, those figures point to a robust market. But the median conceals a market that is increasingly split between winners and losers.
Among more than 1,500 integration companies tracked by D-Tools, 34.8% achieved sales growth of at least 51%. At the same time, 33.4% experienced sales declines of 21% or more. The remaining third of companies were largely flat.
“The market growth is solid, but it’s not the whole story,” said Jason Knott, Data Solution Architect at D-Tools. “Our data shows the market is splitting in two.”
Perhaps most noteworthy is D-Tools’ observation that the divide appears across companies of all sizes. The data does not suggest a simple battle between small and large providers. Instead, the pressure is increasingly concentrated on integrators operating in the upper-middle market.
That finding raises an uncomfortable question: is the traditional mid-sized integration business model becoming harder to sustain?
The clearest evidence emerges when looking at contract sizes. The weakest-performing segment in the D-Tools report was the USD 25,000 – 50,000 average contract category, which declined by 16.1%. No other contract band performed worse. Meanwhile, projects below USD 10,000 grew, and larger contracts above USD 50,000 also expanded.
For decades, the USD 25,000 – 50,000 project represented the bread-and-butter opportunity for many regional integrators. These projects were large enough to require professional design and installation but small enough to be accessible without the scale of a multinational service organisation.
That middle ground now appears to be under attack from both directions.
At the lower end, digital signage and AV solutions are becoming increasingly productised. Displays, media players, software and support services can often be purchased as bundled solutions through manufacturers, IT service providers, telecom operators or even online marketplaces.
At the upper end, enterprise customers are increasingly favouring providers with managed service capabilities, international coverage and lifecycle management expertise. The result is a hollowing out of the market’s traditional center.
Another finding from the D-Tools data reinforces this conclusion. Integrators generated 19% more proposals during the first half of 2026 and signed 17% more contracts. Yet close rates remained essentially unchanged.
In other words, companies are winning more work because they are pursuing more opportunities, not because they are becoming more effective at converting prospects into customers. That points to intensifying competition. Integrators must generate more sales activity simply to maintain growth. More proposals, more bidding and more effort are required to achieve similar conversion rates.
This pattern was already visible in earlier D-Tools benchmark data. During Q1 2025, proposal values increased by 20%, yet average signed-contract values fell by 1%. D-Tools noted a widening gap between proposal and contract values, suggesting increased value engineering, negotiation and pricing pressure.
Taken together, these indicators suggest that market demand remains healthy, but winning profitable business is becoming more difficult.
The competitive landscape has changed dramatically over the past decade. Historically, AV integrators acted as the primary route to market for professional display and collaboration technologies. Today, customers have many more options.
Display manufacturers increasingly offer turnkey solutions that bundle hardware, software and services into a single contract. IT vendors, telecom operators, office technology providers and managed service organisations are all competing for projects that once automatically belonged to specialist integrators.
In digital signage, the shift is particularly visible. Solutions can now be purchased as subscription-based services rather than capital projects. Menu boards may be bundled into POS platforms. Screens may be included in broader workplace or managed-service agreements. For many small and medium-sized customers, simplicity outweighs customisation.
If a telecom provider, IT reseller or display manufacturer can provide a single monthly invoice covering hardware, software, connectivity and support, the traditional integration model becomes harder to distinguish. This trend disproportionately impacts mid-sized providers whose competitive advantage was historically based on project delivery rather than recurring services.
At the opposite end of the market, larger players continue to increase their advantages through consolidation and managed services.
The leading players in the 2026 invidis EMEA ranking increasingly resemble technology service companies rather than traditional AV contractors. Organisations such as Econocom, Cancom, M-Cube, Zetadisplay and Trison combine integration capabilities with managed services, software expertise, financing models and international delivery organisations.
Similarly, North American giants such as Forté, AVI-SPL and Diversified have invested heavily in global coverage, recurring services and customer lifecycle management. Enterprise customers increasingly value consistency, governance, monitoring and operational accountability. Those requirements naturally favour organisations with broader resources and larger service infrastructures.
For mid-market integrators serving regional customers, competing against both global service providers and low-friction turnkey platforms creates a challenging strategic position.
The future belongs to specialists or service providers
The D-Tools data does not suggest that mid-sized integrators are doomed. It does, however, indicate that standing still is becoming increasingly risky. The most successful companies appear to be moving in one of two directions:
Scaling up through acquisitions, managed services and regional or international expansion.
Becoming highly specialised, focusing on vertical expertise, customer experience, software integration or niche market leadership.
The companies struggling are often those caught between these two models.
That helps explain why the industry’s median growth figure tells only part of the story. A 14% increase sounds healthy. Yet underneath that number lies a market where roughly one-third of integrators are thriving, another third are declining sharply, and the traditional middle ground is shrinking.
Study : Why Mid-Sized AV Integrators Are Losing Marketshare
E-Paper : AUO Display Plus Takes Sovereign Signage Mainstream
Samsung VXT : The CMS Is Not the Product – The Ecosystem Is
Three Executive Appointments : Zetadisplay Strengthens Leadership Team
E-Paper Displays : E Ink Invests In Conductive Ink Startup Newcopper